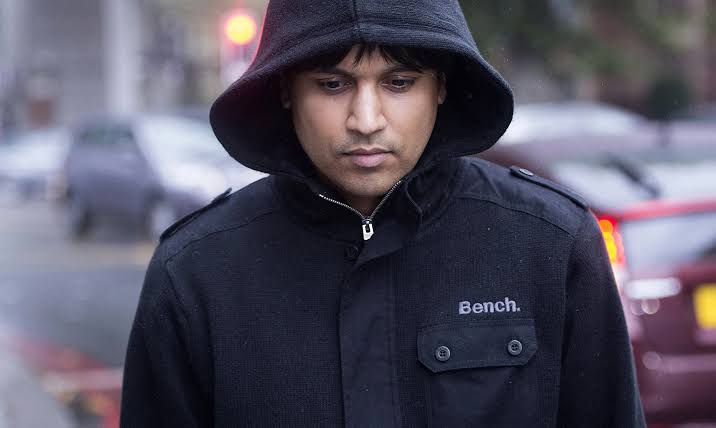
On May 6, 2010, the U.S. stock market suddenly went into free fall. The Dow Jones Industrial Average plunged about 600 points in minutes, while roughly $1 trillion in market value temporarily disappeared before prices rapidly recovered. At first, investigators had no clear explanation. Years later, they found that a little-known futures trader in London had been using an automated strategy that created the appearance of enormous selling pressure. His name was Navinder Singh Sarao, and he had been trading from his parents’ home in Hounslow. He did not cause the entire crash—but his trades became a crucial part of the investigation into how it happened.
The Trader Nobody On Wall Street Knew
Sarao was not sitting on a Wall Street trading floor surrounded by analysts and computer engineers. He was a self-taught trader operating from his parents’ house in west London, specializing in futures contracts tied to the S&P 500.
He focused on the E-mini S&P 500, one of the world’s most heavily traded financial products. Unlike buying shares in a company, these contracts allow traders to speculate on the future level of a stock-market index, and the market is heavily automated.
Sarao became skilled at reading the electronic order book and understanding how other traders reacted to large orders. He eventually developed software that could place large numbers of orders rapidly, allowing him to manipulate the appearance of supply and demand.
That strategy would eventually attract the attention of regulators on both sides of the Atlantic. At the time, however, Sarao was just another trader working quietly from London. Then came May 6, 2010.
Ever wonder how one person in their bedroom crashed the stock market? Discover the wild story behind the 2010 Flash Crash, where a lone trader exploited digital loopholes to rake in millions. Watch this deep dive into the dark side of algorithmic trading and the aftermath that changed financial history!
The Afternoon The Market Suddenly Collapsed
The day began badly but not catastrophically. Investors were already nervous about the European debt crisis, and U.S. markets were under pressure.
Then, shortly after 2:30 p.m. Eastern Time, the market began moving much faster.
The S&P 500 and other major indexes plunged dramatically. The Dow lost about 600 points in roughly five minutes, while some individual stocks briefly traded at absurdly low prices. Within minutes, much of the market recovered.
The event became known as the Flash Crash.
It was unlike a traditional market crash. There was no long buildup over weeks or months. Prices collapsed with extraordinary speed and then largely recovered before the trading day was over.
The episode immediately raised a frightening question: How could a market worth trillions of dollars behave as though someone had pulled the plug? Regulators began reconstructing billions of individual transactions to find out.

The Clue Was Hidden In The Futures Market
At first, investigators looked toward the stock market itself. But their reconstruction eventually led them somewhere else.
The SEC and CFTC determined that the initial disruption was closely connected to the E-mini S&P 500 futures market. A large institutional trader, Waddell & Reed, was selling 75,000 E-mini contracts through an automated program, an order worth roughly $4.1 billion. That selling pressure interacted with already fragile market conditions and rapidly depleted liquidity.
This was an important discovery because it showed that the Flash Crash did not have one simple cause.
The market was already under stress. Liquidity was thin. Automated trading systems were reacting to one another at extraordinary speed. A huge institutional sale then helped push the system into a much more violent imbalance.
But investigators also found another trader whose activity had helped distort that same market. That trader was Sarao.
He Was Creating Orders He Did Not Intend To Fill
The technique that brought Sarao into the investigation was known as spoofing.
The basic idea was to place large orders that created the appearance of strong buying or selling interest without intending those orders to be executed. Other traders could see those orders in the market and react to what appeared to be genuine supply or demand.
Sarao used an automated program that repeatedly created large layers of sell orders in the E-mini market. According to the CFTC, he would place the orders, modify them and cancel them before they were executed, while using genuine trades to profit from the price movements those orders helped create.
The orders were not merely large. There were thousands of them.
According to the CFTC’s later findings, Sarao and his company used their dynamic layering program for a cumulative 4 hours and 25 minutes on the day of the Flash Crash. The orders were modified more than 81,000 times, while only 81 lots from those spoof orders actually resulted in executed trades.
The strategy was designed to influence what other traders believed was happening in the market. And for a while, it worked.
Did One Trader Cause The $1 Trillion Crash?
This is where the story needs an important correction. Sarao did not single-handedly wipe $1 trillion from the U.S. market.
The dramatic figure refers to the amount of market value that temporarily disappeared during the Flash Crash, not money that Sarao personally destroyed or stole. And the SEC and CFTC concluded that there was no single culprit responsible for the event.
Multiple forces were involved: anxious markets, declining liquidity, automated trading, a massive institutional sell order and the interaction of different trading systems.
But regulators also concluded that Sarao’s activities contributed to the extreme imbalance in the E-mini order book and to the market conditions that helped produce the crash.
That distinction makes the story more interesting, not less.Sarao was not the man who controlled the entire U.S. stock market from a bedroom.
He was one trader whose manipulation became entangled with a much larger and more fragile machine.
How Much Money Did He Actually Make?
The numbers surrounding Sarao’s profits are often exaggerated or simplified.
The CFTC said Sarao admitted to using manipulative strategies over several years and making at least $12.8 million in illicit gains. Its 2015 complaint said his overall trading profits from the relevant period exceeded $40 million, while the later court order focused on the amount he admitted to gaining illegally.
Either way, the contrast was striking. The market disruption associated with the Flash Crash involved trillions of dollars in market value. Sarao’s admitted illicit gains were measured in millions.
The scale of the market was enormous. The trader behind one important piece of the story was comparatively small.
The Investigation Took Five Years
The Flash Crash happened in 2010.
Sarao was not arrested until April 2015, when British authorities detained him in London at the request of the United States. By then, American investigators had spent years examining trading records and reconstructing what had happened.
The delay reflected the complexity of the case. Investigators were not simply trying to show that Sarao placed large orders. They needed to demonstrate that many of those orders had been entered without an intention to trade and had been used to manipulate the market.
The evidence ultimately included years of electronic trading records. A strategy that could be executed in milliseconds left behind an enormous digital footprint. The speed that made the trading difficult to see in real time eventually became an advantage for investigators examining the data afterward.
Sarao Pleaded Guilty
Sarao was extradited from Britain to the United States in November 2016.
That same month, he pleaded guilty to one count of wire fraud and one count of spoofing. According to the Justice Department, he admitted that from at least 2009 through 2014 he used an automated program and other techniques to manipulate E-mini S&P 500 futures.
The original case had contained 22 counts, but the final guilty plea was much narrower.
Sarao also agreed to forfeit money connected to the illegal trading. In a separate CFTC case, a federal court ordered him to pay more than $38.6 million in civil monetary sanctions and disgorgement and permanently banned him from trading and registering with the agency.
His criminal case ultimately ended with a sentence of time served, allowing him to return to the United Kingdom. The legal outcome was far less dramatic than the headline surrounding the Flash Crash. But the case had already changed how regulators thought about electronic markets.
The Crash Changed Market Rules Too
The Flash Crash exposed how quickly modern markets could become unstable when automated systems interacted under stressed conditions.
After the event, U.S. regulators introduced and strengthened safeguards designed to slow or interrupt extreme price movements. Market-wide circuit breakers and other “time-out” mechanisms were developed to give markets a chance to recover when trading became disorderly. The case also helped establish spoofing as a major enforcement issue.
Electronic markets could move faster than any human trader could follow, but every order still produced a digital record. That created a new form of financial investigation: rather than finding physical evidence, regulators could reconstruct what happened by studying the sequence of orders, cancellations and executions. The market had become a machine. Investigators learned how to read its logs.
A Bedroom Trader Who Became Part Of Market History
Navinder Singh Sarao’s story remains compelling because of the mismatch between his surroundings and the market he influenced.
He was not a famous hedge-fund manager. He did not run a major investment bank. He operated from his parents’ home in Hounslow, using software to trade a financial product thousands of miles away in Chicago.
Yet his activity became part of the investigation into one of the most dramatic trading disruptions in American financial history.
The full story is more complicated than the popular version. Sarao did not make $1 trillion disappear. He did not single-handedly cause the Flash Crash. Regulators found that the event resulted from multiple interacting factors.
But he did use thousands of fake orders to create a false picture of supply and demand, profited from the resulting market reactions and ultimately pleaded guilty to spoofing and wire fraud. That leaves a remarkable lesson behind.
In a market where billions of dollars can move in seconds, a trader does not necessarily need a giant company or a Wall Street office to make a noticeable impact.
Sometimes, all it takes is a computer, a sophisticated strategy—and a system moving fast enough that almost nobody can see what is happening until afterward.
Navinder Singh Sarao became famous after U.S. authorities linked his trading to the May 6, 2010 Flash Crash, when major U.S. indexes plunged rapidly and roughly $1 trillion in market value temporarily disappeared before recovering. Sarao was not responsible for the entire crash, and regulators concluded that multiple factors were involved. But he admitted using thousands of spoof orders to create a false impression of supply and demand in E-mini S&P 500 futures, sometimes profiting from the market reactions those orders produced. The investigation eventually led to his arrest in London in 2015 and his guilty plea to wire fraud and spoofing in 2016. His story became an unusual chapter in financial history: a self-taught trader operating from his parents’ bedroom had become part of the investigation into a market failure that briefly stunned the world.
P.S. This story draws on NDTV’s profile of Navinder Singh Sarao, together with U.S. Department of Justice and CFTC records on his trading, guilty plea and role in the Flash Crash. Sources: NDTV; U.S. Department of Justice; Commodity Futures Trading Commission; SEC – https://www.ndtv.com/feature/navinder-singh-sarao-how-this-indian-trader-wiped-off-1-trillion-from-us-market-5062729