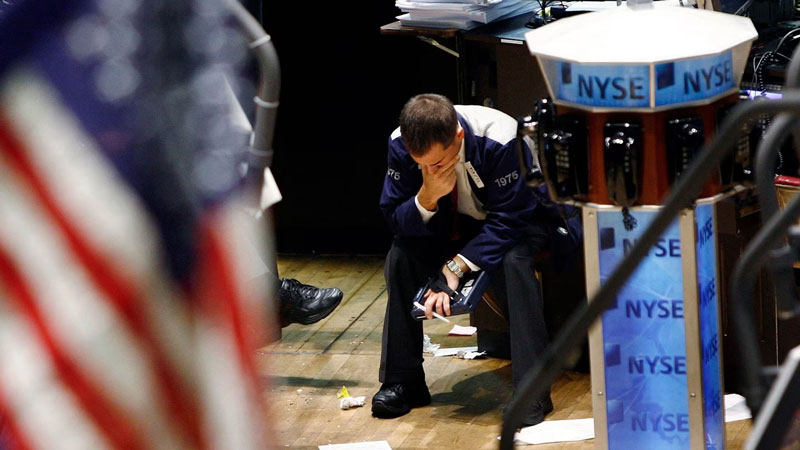
Losing a million dollars is a disaster for most investors. Losing a billion is the kind of event that can destroy a financial institution. Yet in July 2026, an AI-focused investment fund became associated with a loss of roughly $35 billion, putting it at the top of a widely cited historical leaderboard of trading disasters. The remarkable part is not only the size of the loss. It is how quickly a highly successful investment strategy can turn into a forced liquidation when concentration and leverage leave little room for a mistake.
The $35 Billion Loss That Started With A Winning Bet
The latest entry on the leaderboard is Situational Awareness, a fund founded by former OpenAI researcher Leopold Aschenbrenner. Its strategy was heavily focused on the companies supplying the infrastructure behind the artificial-intelligence boom, including semiconductor, data-center and related technology businesses.
For a while, the strategy worked spectacularly. According to reporting cited by Financial Times coverage, the fund gained about 439% in the first half of 2026 and reached roughly $45 billion in assets at its peak after borrowing amplified the size of its positions.
Then the market moved the other way.
The fund’s concentrated positions were hit by a sharp decline in several AI-related stocks. Because leverage had magnified the original gains, it also magnified the losses. Margin calls then forced the fund to sell much of its public-equity portfolio, contributing to a roughly $35 billion decline in assets over the episode.
That is what makes the story so striking: the disaster did not begin with an obviously irrational investment. It began with a thesis that had been extremely profitable.
How did a 24-year-old go from managing $45 billion to a total market collapse in just one month? The story of Situational Awareness is a wild ride through AI hype, extreme leverage, and one of the biggest Wall Street implosions in history. Don’t miss this breakdown.
How A Great Trade Turns Into A Disaster
The Financial Times’ leaderboard points toward a deceptively simple explanation for enormous trading losses: first, someone has to persuade investors or institutions to entrust them with enormous amounts of money. Then comes the more dangerous part—building a high-conviction trade and allowing leverage or weak risk controls to magnify the outcome.
Leverage changes the meaning of a market decline.
An investor holding a stock without borrowed money can potentially wait through a temporary fall. A heavily leveraged investor may not have that luxury. Once the value of the collateral falls far enough, lenders can demand additional capital or require positions to be sold.
That creates a vicious cycle. Falling prices produce margin pressure, margin pressure forces sales, and those sales can push prices lower still. Even if the original investment thesis eventually turns out to be correct, the investor may be forced out before having the opportunity to find out.
That is one of the central lessons behind the largest trading losses in history: being right about the long-term idea is not enough if the financing structure prevents you from surviving the short-term move.

The Biggest Losses Were Not All Hedge Funds
The leaderboard also reveals something surprising.
People often imagine the greatest trading disasters as rogue hedge-fund managers making giant bets. But among the top 25 losses, only seven are attributed to hedge funds. Many of the others came from banks and corporations that suffered enormous losses through derivatives, credit products or failed hedging strategies.
One of the most famous examples is Morgan Stanley, where losses associated with credit-default swaps reached about $9 billion in 2008. JPMorgan Chase suffered another roughly $9 billion loss from credit-default swaps in 2012, in the episode that became known as the “London Whale” affair.
In 2008, trader Jérôme Kerviel caused Société Générale to lose the equivalent of more than $7 billion through unauthorized positions in European equity-index futures. Two years earlier, hedge-fund manager Brian Hunter lost about $6.5 billion at Amaranth Advisors after enormous natural-gas positions moved against the fund.
And some of the biggest disasters came from bets that were not even obvious high-risk speculation at first glance. Long-Term Capital Management, for example, had assembled a sophisticated bond-arbitrage strategy based on the expectation that price relationships would converge. When markets behaved very differently during the 1998 Russian financial crisis, the fund’s losses became severe enough to threaten broader financial stability.
The common thread was not simply reckless gambling. It was the combination of size, complexity, leverage and a position that became impossible to unwind safely.
Some Traders Lost Billions In Very Different Ways
The leaderboard includes several spectacular examples of how markets can punish a concentrated position.
In 2021, Archegos Capital Management collapsed after using derivatives called total-return swaps to build enormous exposure to a relatively small group of stocks. The resulting losses were estimated at around $10 billion, making it one of the largest recorded trading failures.
In 2022, Chinese metals company Tsingshan Holding Group faced an enormous loss on short positions in nickel as prices surged. The position reportedly reached about $8 billion in losses at the time.
Then there was Amaranth Advisors, whose natural-gas strategy produced roughly $6.5 billion in losses in 2006. The fund had become heavily exposed to an energy market that moved sharply against it, wiping out most of its capital in a matter of weeks.
These stories look different on the surface, but their underlying problem is familiar: a position becomes so large relative to available capital that a market move stops being an ordinary loss and becomes an existential event.
At that point, the question is no longer whether the trade will eventually recover. It is whether the investor can remain in the trade long enough to find out.
Even The Leaderboard Has A Blind Spot
There is an important caveat to all of these rankings.
The financial world is not completely transparent, especially when private investment funds and proprietary trading operations are involved. The Financial Times notes that such a leaderboard is likely to capture the losses that become public and make compelling stories, not necessarily every loss that has ever occurred.
That means the rankings should not be treated as a perfect measurement of every financial disaster.
For example, the Financial Times commentary highlights the roughly $40 billion decline associated with Tiger Global in 2022 as a case that could arguably deserve a much higher position, depending on how losses are defined. It also mentions a reported roughly $15 billion hit at Jane Street linked to turmoil around Situational Awareness, illustrating how the distinction between an individual fund’s trading loss, a decline in asset value and losses experienced by counterparties can become complicated.
This is why the numbers require some caution. A “trading loss” can mean different things depending on whether someone is measuring realized losses, mark-to-market declines, assets destroyed, losses passed to counterparties or the ultimate economic cost of a failed strategy.
The bigger picture, however, remains clear. The largest financial disasters are often created when an enormous position meets a market move that the investor cannot survive.
The Real Enemy Is Often Not The Market
The most useful lesson from these spectacular failures is not that markets are unpredictable. Everyone who trades already knows that.
The deeper problem is position size. A trade can be fundamentally sensible and still become disastrous if too much capital is committed to it. A manager can correctly identify an industry trend, correctly understand a company’s long-term prospects and still lose enormous sums because the market moves against the position at precisely the wrong moment.
Leverage makes that danger more extreme because it removes time—the one resource a long-term investor needs most.
That is why the story of the largest trading losses is ultimately less about greed than about survival. Once a position becomes too large, a temporary market movement can become a forced decision. And after a forced sale, there is no guarantee that the investor will ever get the chance to participate in the recovery.
The billions disappear not necessarily because the original idea was worthless, but because the structure of the bet was too fragile to withstand being wrong for long enough.
The world’s largest trading losses are not simply stories about people making bad bets. They are stories about what happens when enormous capital, concentrated positions and leverage collide with an unexpected market move. Situational Awareness’ roughly $35 billion loss in 2026 is the latest dramatic example, but the pattern has appeared repeatedly in the histories of Archegos, Amaranth, Long-Term Capital Management, Société Générale and major banks. The lesson is remarkably consistent: in finance, being right eventually may not matter if a position is large enough to force you out before “eventually” arrives.
P.S. This article is based primarily on the Financial Times leaderboard of major trading losses, with supporting information from the underlying historical trading-loss data and recent reporting on the 2026 Situational Awareness collapse. Source: https://www.ft.com/content/340bf9e7-0e67-4d19-b671-3dc8186efb99